Banking
Regulated work, trusted people.
Branch and operations staff, credit analysts, KYC and financial crime, risk and compliance, and payments for banks, credit unions and lenders. Screened for the regulations you answer to and the trust your customers place in you.
- 6 functions
- from the branch and loan operations through credit, financial crime, risk and payments
- Background ready
- background and fingerprinting requirements for regulated institutions completed before day one
- Regulation first
- screened on the rules behind the procedure, not only on the system they used
Banking
In banking, trust is screened before skill.
We staff banks, credit unions and lenders: branch and retail banking, loan and deposit operations, credit and underwriting, KYC, AML and fraud, risk and regulatory compliance, and payments operations.
Banking puts a gate on every hire that most industries do not. Regulated institutions carry background and fingerprinting requirements, and some convictions bar employment outright. We complete those checks to your standard before anyone starts, not after.
The second filter is the regulation behind the work. A loan processor who knows why a TRID timeline matters, or an analyst who has written a suspicious activity report that stood up to review, is a different hire from one who has only used the system. We screen for that difference.
Functions
What we actually recruit for.
Pick one and you get what they actually produce, the seniority we fill, and the tools and standards a screen has to cover.
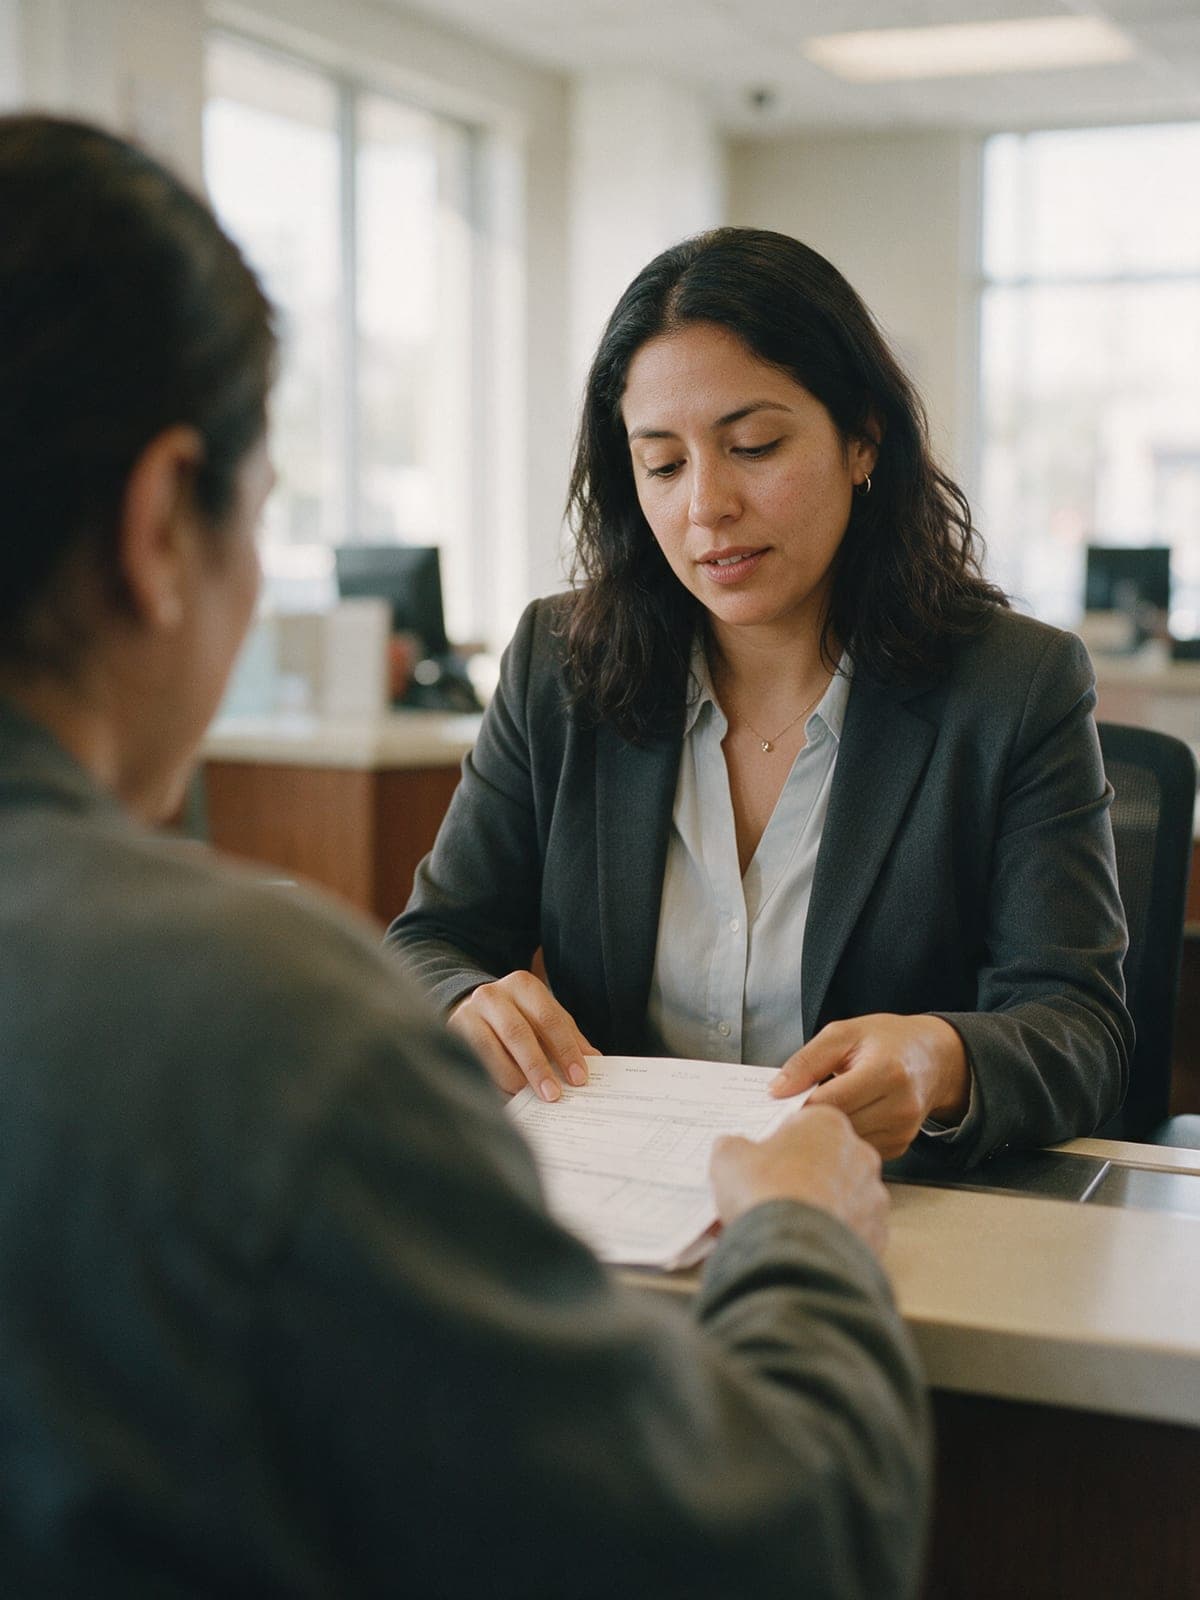
Account opening, cash handling, customer service and the conversations that keep a customer at the branch rather than at a competitor.
- Seniority we fill
- Teller and personal banker through to branch manager
- Tools
- Teller and branch platformsFiserv, FIS and Jack Henry coresCRM systemsCash recyclers
- Standards
- CIP and KYC at account openingRegulation CC and Regulation ECash handling and dual control
The vocabulary
What we recruit against.
Regulation, system and authority. Those three questions decide almost every banking shortlist we build.
Core and branch systems
- Fiserv
- FIS
- Jack Henry
- Temenos
- Teller platforms
Lending and credit
- nCino
- Encompass
- Moody's CreditLens
- Abrigo
- Desktop Underwriter
Financial crime
- NICE Actimize
- Verafin
- World-Check
- LexisNexis
- Oracle FCCM
Regulation
- BSA and AML
- OFAC
- TRID
- Regulation B
- Regulation E
- FFIEC
- Nacha
- PCI DSS
Anyone can learn the system. The useful question is what they did the last time something in a file did not add up.
Screening
How we screen for a bank.
Banking screening has a trust gate and a regulation gate. Skill matters, but on its own it does not make somebody safe to put in front of your customers and their money.
- 01
Background and eligibility checked
Criminal, credit where permitted, employment verification and fingerprinting to your institution's standard, with FDIC Section 19 in mind. Completed before the start date.
- 02
Regulation named
Which rules the candidate has actually worked under: BSA and AML, lending and consumer regulations, payments rules. Familiarity is not the same as accountability.
- 03
Systems confirmed
The core, lending, credit or financial crime platform they used, and whether they operated it, reviewed in it or administered it.
- 04
Judgement tested in context
A walk through of an alert they escalated, a file they declined or an exception they caught. The detail of the answer shows whether they understand the risk behind the procedure.
- 05
A reference from a reviewer or manager
Somebody who checked their work: a QC reviewer, a credit officer or a compliance lead, not only a peer.
Straight answer
Where the market is actually tight.
What our recruiters see running these searches. Experience rather than a guarantee.
| Role | What the market looks like | Realistic shortlist |
|---|---|---|
| Tellers and branch staff | Available in most markets, with turnover the real challenge. | One to two weeks |
| Loan and deposit operations | Available in most banking centres. System specific experience narrows it. | One to three weeks |
| KYC and AML analysts | Steady supply at entry level, much thinner for investigations and SAR writing. | Two to four weeks |
| Payments operations | Tight for wire and ACH exception experience. | Three to four weeks |
| Commercial credit analysts | Competitive, particularly with spreading and credit memo experience. | Three to five weeks |
| Senior compliance and BSA officers | The hardest banking hire we run, and largely national. | Six weeks and up |
Remediation programmes and exam findings create sudden demand across the whole market at once. If your timeline is driven by a regulator, tell us early and we will plan the search around the date.
Shapes
Three shapes this usually takes.
Banking demand is driven by remediation, conversions and volume.
Remediation and look back team
KYC, AML and compliance analysts for a defined review population.
- When it fits
- A consent order or exam finding, a KYC refresh, an alert backlog.
- The arrangement
- Contract, scoped to the review, with a clear end date and QC built in.
Conversion and integration
Operations and system specialists for a core conversion or a merger.
- When it fits
- A core conversion, a branch or portfolio acquisition, a new lending platform.
- The arrangement
- Contract or contract-to-hire, with the option to keep the people who learn the new platform best.
Branch and operations volume cover
Tellers, processors and operations staff for a surge or a backlog.
- When it fits
- Rate driven refinance waves, seasonal volume, leave cover in a critical queue.
- The arrangement
- Temporary or contract-to-hire, with background checks complete before day one.
Before you call
What to have ready before you call.
Five specifics here are worth more than a full job description.
- Your background, fingerprinting and credit check requirements
- The core, lending, credit or financial crime platforms in use
- The regulations the role is accountable to
- Whether the role performs, reviews or approves the work
- On site, hybrid or remote, and any data access restrictions
- The rate or salary band, and any regulator driven deadline
Open roles
A sample of banking roles we fill.
Questions
Before you call.
Yes. Criminal, employment and education verification, credit where permitted, and fingerprinting where your institution requires it, all completed before the start date and with FDIC Section 19 in mind.
Remediation, conversion or a busy season?
Tell us the regulation, the system and the deadline. We will tell you honestly how fast the right people can start.